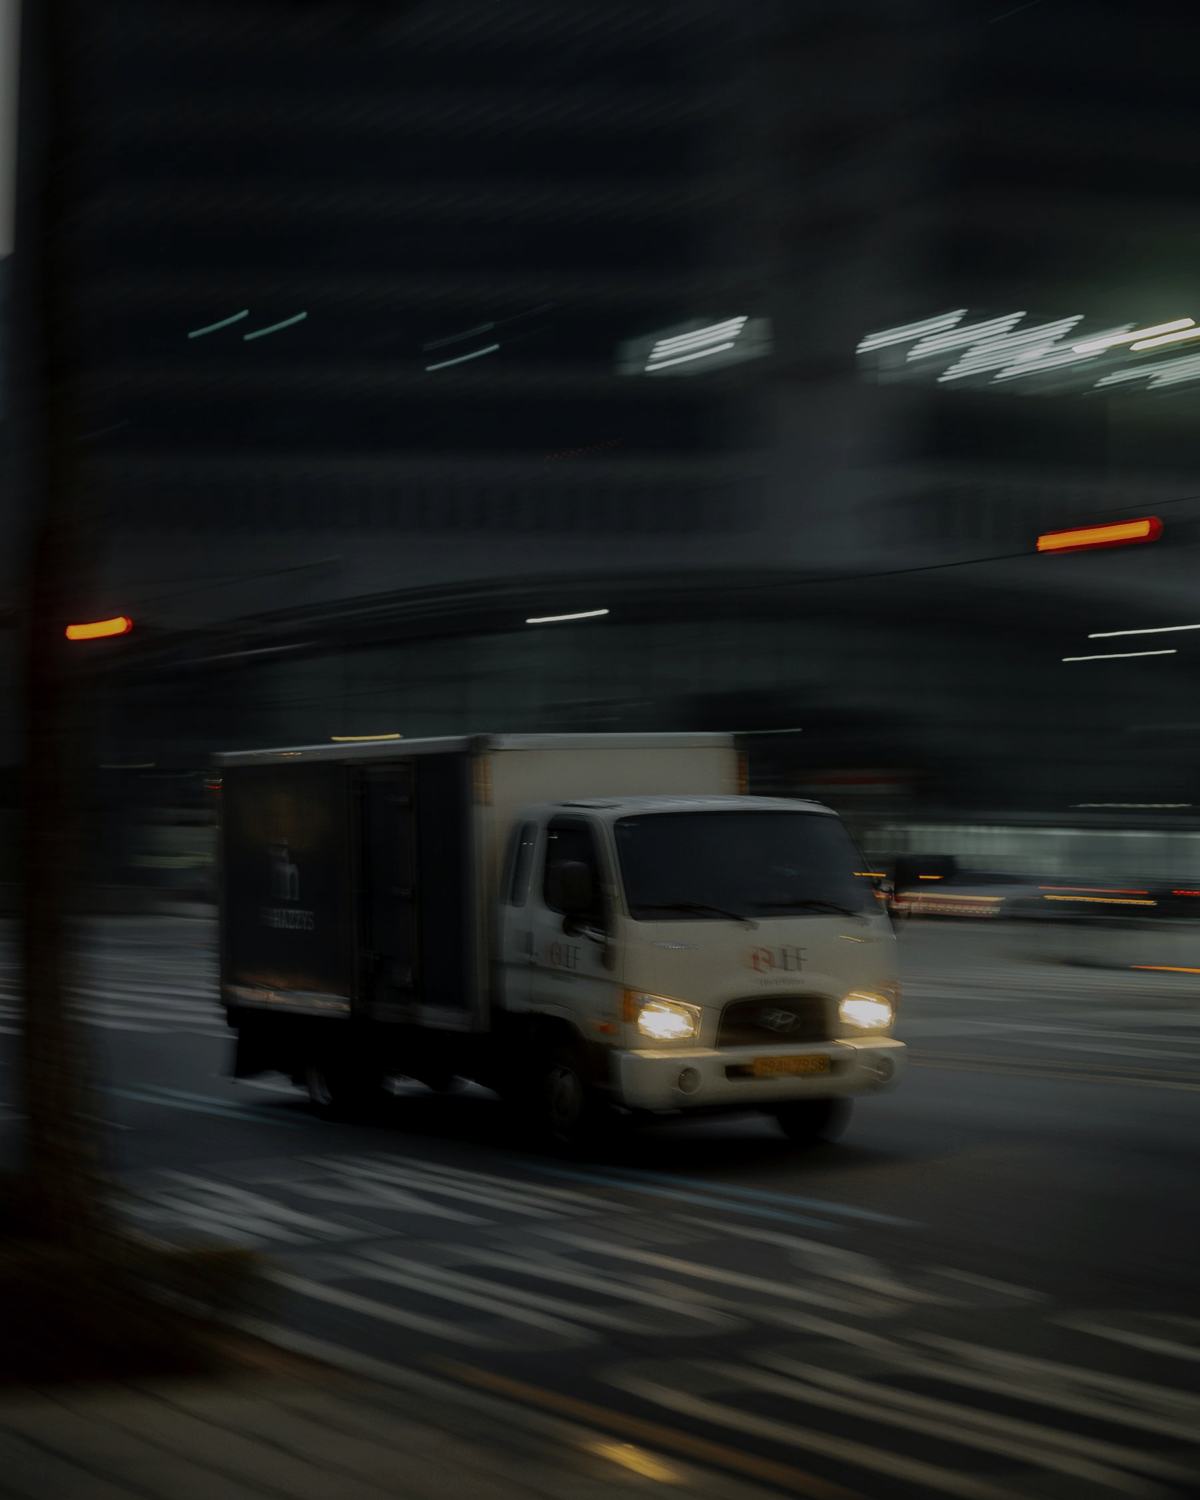
Delhivery reported revenue from services of Rs 3,066 crore in the September quarter of FY27, up 20% year on year, and consolidated net profit of Rs 41 crore. The logistics company announced the results on October 30. Its first quarter above Rs 3,000 crore in revenue puts attention on whether growing parcel and freight volumes can translate into sustained profitability.
The company reported EBITDA of Rs 205 crore, roughly three times the year-earlier level, with an EBITDA margin of 6.7%. Consolidated profit after tax represented a 1.3% margin. Revenue, operating profit and net profit measure different things: a larger shipment network does not by itself guarantee a large bottom-line margin.
Express parcel volume reached 325 million shipments, up 32% year on year, while revenue from that business rose 22%. Part Truck Load volume was 545,000 tonnes, up 14%, with revenue increasing 23%. These company-reported figures show growth across parcel delivery and freight consolidation, rather than one isolated line of business.
Delhivery said its early AI investments were helping sales productivity, customer onboarding, claims and dispute resolution, and fraud detection. Its in-house robotics lab has started producing customised autonomous vehicles for movement inside facilities. Other robotics systems remain in testing. These are management-reported developments, not independent proof of a particular productivity gain.
FundForge Insight: the useful test is the quality of growth. Higher volumes need to be matched by reliable service, cost control and repeat customer demand. Delhivery flagged fuel prices, labour availability and statutory changes as operating pressures. A 1.3% net profit margin leaves execution important even after a stronger quarter; the results do not remove those risks.
Sources: Delhivery's October 30 Q2 FY27 press release and investor-relations disclosures; Moneycontrol, October 30; CNBC-TV18, October 30; and YourStory, October 30. All operating figures above are company-reported and rounded as in the release. Hero: original FundForge typographic artwork; no third-party photograph. News analysis, not investment advice.